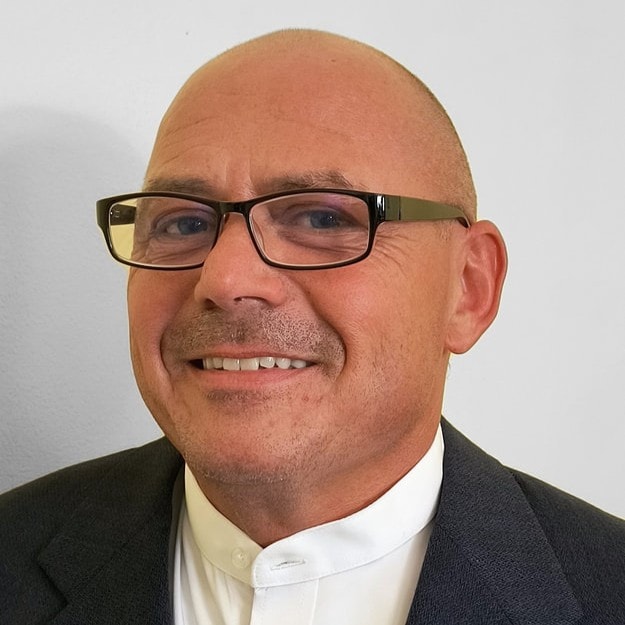
Your Independent Medicare Broker
William Gray
Founder of The Medicare Dude · Licensed Since 1998 · Independent Medicare Broker
Independent Medicare enrollment guidance for Florida residents approaching 65.
"Very Knowledgable and personable! William made a seemingly difficult transition easy and seamless. I appreciated his unbiased opinion and personalized what was best for me. He took great care in listening to my concerns. I never felt rushed and felt he took a personal interest in assisting me to make the best choice. Not one of those "Big box" sales as seen on TV. Highly recommend William."
Sharon H
Medicare client
5 ★ · 94 reviews
Florida Medicare enrollment guidance
Turning 65 in Florida? Plan Your Medicare Next Steps
Florida residents approaching 65 can use the national Medicare enrollment timeline as their starting point, then prepare for the local coverage research that follows. The Medicare Dude provides independent guidance to help you organize the questions that matter before you enroll and before you compare coverage choices.
Call (386) 871-3858See real-time Medicare Supplement rates in Florida
Compare Plan G and Plan N premiums from multiple carriers — no obligation.
Start with your Medicare enrollment timing
Your Initial Enrollment Period is the first place to start. It generally centers on the month you turn 65, but the right action can depend on whether you are already receiving Social Security or Railroad Retirement Board benefits, whether you have employer coverage, and when that coverage will end.
If you are already receiving Social Security or Railroad Retirement Board benefits before 65, Medicare Part A and Part B enrollment may happen automatically. If you are not receiving those benefits, you will generally need to take action through Social Security. Confirm your own situation directly with Social Security rather than assuming enrollment is automatic.
Employer coverage and HSA questions deserve an early review
If you or your spouse has employer coverage, ask the benefits office how that coverage works with Medicare before delaying Part B. The size of the employer and the type of coverage can affect the questions you need to resolve. Keep records of creditable coverage and enrollment decisions.
If you contribute to a Health Savings Account, review Medicare timing before you enroll. Medicare enrollment can affect HSA contribution eligibility, and the timing can be important. A tax professional and the official Medicare and Social Security resources can help you confirm how the rules apply to you.
Coverage choices come after the enrollment path is clear
Once you understand your enrollment timing, you can compare coverage paths. That is the point to consider Original Medicare with a Medicare Supplement and Part D plan, or Medicare Advantage, based on your doctors, prescriptions, budget, travel, and comfort with provider networks.
In Florida, Medicare Advantage and Part D availability can vary by county, ZIP code, carrier, plan, eligibility, and service area. Use your actual residence and medications when researching options. This page does not represent every plan or insurer, and no plan availability or enrollment outcome is guaranteed.
Florida resources and independent help
Florida SHINE is the state Health Insurance Assistance Program and offers free, unbiased Medicare counseling. Medicare.gov and the Social Security Administration remain the primary official sources for enrollment rules and government processes.
William Gray is licensed in Florida (License #W690237) and can help you prepare questions, understand the timing sequence, and move into coverage research when you are ready. Assistance is limited to locations, products, carriers, and plans where the agency is appropriately licensed, authorized, and appointed.
Your Medigap Open Enrollment Period — separate from your Medicare IEP
Your Medicare Initial Enrollment Period (IEP) is about when you sign up for Part A and Part B. Your Medigap Open Enrollment Period (OEP) is a different window — and it is the most important time to buy a Medicare Supplement policy.
The Medigap OEP is a six-month window that begins the month you are both age 65 or older and enrolled in Medicare Part B. During this window, any insurance company selling Medigap in Florida must accept you at standard rates, regardless of your health history. They cannot ask health questions, deny you coverage, or charge more because of a pre-existing condition.
Outside of this window, Florida insurers can use medical underwriting — meaning they can ask about your health, charge higher premiums, or decline your application. Guaranteed-issue rights can reopen a protected window in specific situations, but they are not a substitute for acting during your OEP.
The practical implication: if you are approaching 65 in Florida and considering a Medicare Supplement policy, the Medigap OEP is the window to act. Missing it does not mean you can never get Medigap, but it can make the process more difficult and more expensive.
Not sure where to start?
Call William Gray — licensed in Florida and independent of any carrier. He can help you sort out enrollment timing, employer coverage questions, and coverage choices before your window closes.
Florida Medicare Supplement resources
When you are ready to choose coverage
After your enrollment path is clear, compare the coverage choices that fit your doctors, prescriptions, budget, travel, and network preferences. Compare Medicare coverage choices at 65.
For general Florida Medicare guidance beyond the Turning-65 enrollment path, visit the Florida Medicare insurance guide.
Medicare Supplement Resources
Official resources for Florida residents
Talk through your Florida Medicare next steps
Get independent guidance on the questions to resolve before enrollment and before you compare coverage options.
The Medicare Dude is not affiliated with or endorsed by the U.S. government or the federal Medicare program. Assistance is limited to locations, products, carriers, and plans where the agency is appropriately licensed, authorized, and appointed. Availability varies by state, county, ZIP code, carrier, plan, eligibility, and service area. No savings, eligibility, enrollment, acceptance, or availability is guaranteed.