Medicare Supplement Guidance in Jacksonville, FL
Turning 65 in Jacksonville? The Medicare enrollment decisions you make in the next few months — which plans you choose, when you enroll, and how you time your transition from employer coverage — can affect your coverage options for years. William Gray is an independent Medicare agent licensed in Florida (W690237). When you call (386) 871-3858, you speak directly with William.
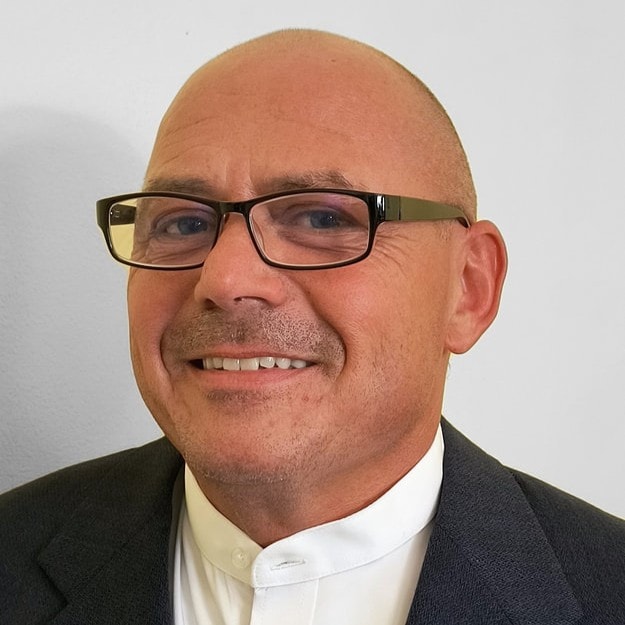
Your Independent Medicare Broker
William Gray
Founder of The Medicare Dude · Licensed Since 1998 · Independent Medicare Broker
"I personally return every call."
Independent Medicare Supplement Agent serving Jacksonville, Florida
"Very Knowledgable and personable! William made a seemingly difficult transition easy and seamless. I appreciated his unbiased opinion and personalized what was best for me. He took great care in listening to my concerns. I never felt rushed and felt he took a personal interest in assisting me to make the best choice. Not one of those "Big box" sales as seen on TV. Highly recommend William."
Sharon H
Medicare client
5 ★ · 94 reviews
Medicare in Jacksonville
Jacksonville's size and geography matter for Medicare Advantage and Part D comparisons. Plan service areas, provider networks, pharmacies, and formularies can vary across Duval County ZIP codes. A residential address and ZIP code help confirm the specific plans and costs available to you.
Medicare decisions in Jacksonville often involve more than a monthly premium. A complete review considers whether your preferred doctors participate in a plan's network, how your prescriptions are covered, what cost-sharing applies for specialist visits and hospital stays, and whether the coverage approach fits your expected use of care.
Jacksonville and Duval County
Jacksonville is the county seat of Duval County (FIPS 12031). For Medicare Advantage and Part D, county and ZIP information help establish the local context — the plans available in Jacksonville are the same plans available throughout Duval County, but individual ZIP codes can affect which specific plan options appear in a comparison.
Duval County residents can also review the difference between Original Medicare and Medicare Advantage before evaluating specific plans. An independent broker can walk through both approaches without favoring either.
Turning 65 in Jacksonville — Your Enrollment Timeline
Your Initial Enrollment Period (IEP) begins three months before the month you turn 65 and extends three months after — a seven-month window to enroll in Medicare Parts A and B. If you enroll in Part B during your IEP, your six-month Medigap Open Enrollment Period begins on the first day of the month in which you are both age 65 or older and enrolled in Part B.
During this Medigap Open Enrollment Period, federal guaranteed-issue rights apply — insurers cannot use medical underwriting to deny coverage or charge higher premiums based on your health history. This is the most favorable window to purchase a Medicare Supplement plan. Missing this window does not eliminate your options, but it changes them — outside the OEP, Florida insurers may apply medical underwriting.
Jacksonville residents turning 65 have two main paths. The first is Original Medicare (Parts A and B) with a Medicare Supplement plan and a standalone Part D prescription drug plan. The second is Medicare Advantage (Part C), which bundles hospital, medical, and usually drug coverage through a private insurer. The right path depends on your doctors, prescriptions, expected use of care, and how you want to manage out-of-pocket costs.
Medicare Part A and Part B — What You Need to Know Before You Enroll
Medicare Part A covers inpatient hospital care, skilled nursing facility care, hospice, and some home health services. Most people do not pay a premium for Part A if they or their spouse paid Medicare taxes for at least 10 years. Medicare Part B covers outpatient medical services, doctor visits, preventive care, and durable medical equipment.
Part B has a monthly premium ($202.90 in 2026 for most beneficiaries) and an annual deductible ($283 in 2026). You must be enrolled in both Part A and Part B before a Medicare Supplement plan takes effect. If you are still covered by employer insurance when you turn 65, you may have a Special Enrollment Period that allows you to delay Part B without penalty — but the rules depend on the size of your employer and whether you are the primary insured.
Retiring from Employer Coverage — Timing Your Transition
If you are retiring from a job that provided health insurance, the transition to Medicare requires careful timing. The key questions are: Is your employer coverage primary or secondary to Medicare? How long does your employer coverage last after your retirement date? And does your employer offer retiree health benefits that coordinate with Medicare?
When you lose employer coverage, you typically have a Special Enrollment Period — usually eight months — to enroll in Medicare Part B without a late-enrollment penalty. However, COBRA coverage does not count as employer-sponsored coverage for this purpose. If you rely on COBRA after retirement and delay Part B enrollment, you may face a permanent premium penalty.
Retirees who want a Medicare Supplement plan also need to understand the timing of their guaranteed-issue rights. When you lose employer or group coverage, a federal guaranteed-issue right typically applies for a limited window — usually 63 days. Outside that window, Florida insurers may apply medical underwriting. Reviewing your options before your employer coverage ends is the most important step you can take.
Guaranteed-Issue Rights — When They Apply and When They Don't
Federal guaranteed-issue rights give you the right to purchase certain Medicare Supplement plans without medical underwriting in specific situations. These rights apply during your Medigap Open Enrollment Period, when you lose employer or group coverage in certain qualifying circumstances, and in other specific triggering events defined by federal law.
Guaranteed-issue rights do not apply universally — they are tied to specific triggering events. Outside a qualifying event, Florida insurers may ask health questions and may decline coverage based on your health history. An independent agent can help you determine whether a guaranteed-issue right applies to your situation before you make any enrollment decisions.
Florida does not currently have a general Birthday Rule that allows beneficiaries to switch Medigap plans without underwriting each year. Some other states have enacted such protections, but Florida has not.
Moving to Jacksonville with Medicare
If you are moving to Jacksonville from another state, your Medicare Part A and Part B coverage travels with you — Original Medicare is a national program. However, your Medicare Supplement plan may not follow you seamlessly. Some Medigap carriers restrict coverage to a specific state or region, and your current plan may not be available in Florida. Moving is a qualifying event that may trigger guaranteed-issue rights for a new Medigap plan in Florida, depending on your circumstances.
Medicare Advantage plans are county-specific. If you move to Duval County and your current Medicare Advantage plan does not serve the Jacksonville area, you will have a Special Enrollment Period to choose a new plan. Moving to a new service area is one of the qualifying events that allows you to switch Medicare Advantage plans outside the annual enrollment window.
If you are moving to Jacksonville from a state with a Medigap Birthday Rule — such as California, Oregon, or Missouri — you should understand that Florida does not have a Birthday Rule. Once you are enrolled in a Florida Medigap plan, switching plans outside a qualifying event will typically require medical underwriting. Reviewing your options before your move, while you may still have guaranteed-issue rights, is the most important step.
What to Expect When You Work With William
William Gray is an independent Medicare insurance agent licensed in Florida (W690237) since 1998. He is not a call center. When you call (386) 871-3858, you speak directly with William. He will review your situation — your enrollment timeline, your current coverage, your doctors and prescriptions — and help you understand your options without pressure.
After enrollment, William remains your point of contact. If your plan changes, your premium increases, or your situation changes, you can call him directly. He serves clients throughout Jacksonville, Duval County, and the surrounding northeast Florida region. His services are free to you; he may receive carrier compensation when a policy is issued.
Medigap Resources
Nearby Communities
Frequently Asked Questions
When does my Medigap Open Enrollment Period start?
Your federal six-month Medigap Open Enrollment Period begins the first month you are 65 or older and enrolled in Medicare Part B. During that period, insurers cannot deny an offered policy or charge more because of your health history. This window is separate from Medicare's seven-month Initial Enrollment Period for Parts A and B.
I retired years ago and my Part B started then. Can I still get a Medigap plan without underwriting?
If your Medigap Open Enrollment Period has passed, Florida insurers may apply medical underwriting. Ending retiree supplemental coverage does not automatically restart Medigap open enrollment. The key distinction is whether you are losing active employment coverage (which may trigger a Special Enrollment Period for Part B) versus ending retiree supplemental coverage (which generally does not). Event-specific guaranteed-issue rights apply in defined circumstances — an independent agent can review whether a qualifying event applies to your situation.
Does the October 15 – December 7 Medicare open enrollment period apply to Medigap?
No. The October 15 – December 7 Annual Enrollment Period applies to Medicare Advantage and Part D prescription drug plans — not Medicare Supplement plans. Medigap enrollment is governed by your individual Medigap Open Enrollment Period and applicable guaranteed-issue rights, not the fall enrollment window.
I am leaving employer coverage. Do I have guaranteed-issue rights for a Medigap plan?
Losing active employer-sponsored coverage in certain qualifying circumstances can trigger federal guaranteed-issue rights for specific Medigap plan letters. The applicable protection depends on the type of coverage you are losing, the triggering event, and your Medicare eligibility date. COBRA coverage is not active employer-sponsored coverage for this purpose. Reviewing your options before your employer coverage ends is the most important step — an independent agent can help you determine what rights apply.
Should I cancel my current coverage before applying for a Medigap plan?
Never cancel existing coverage before your Medigap application is accepted and you have a confirmed effective date. Coordinate the end of your current coverage with the start of your new plan to avoid a gap. An independent agent can help you sequence the transition.
I am moving to Jacksonville from another state. Does my Medicare Supplement plan come with me?
Medicare Part A and Part B travel with you anywhere in the country. However, some Medicare Supplement plans have geographic restrictions. If your current Medigap plan does not cover Florida, moving may trigger guaranteed-issue rights for a new Florida plan — but the specific rights depend on your plan type and circumstances. Medicare Advantage plans are county-specific and do not follow you to a new service area; moving to Duval County gives you a Special Enrollment Period to choose a new plan. Reviewing your coverage before your move is the best approach.
What should I bring to a consultation with William?
Your Medicare card (with Part A and Part B effective dates), any existing coverage details and termination notices, your residential ZIP code, your desired effective date, a list of your doctors and their specialties, and your current prescriptions with dosages. Use the secure intake form for sensitive information.
Want to understand how independent Medicare help works? Learn what a Medicare broker does before choosing help with your coverage.
Direct Personal Service
Work Directly With William in Jacksonville
Nearly 30 years of Medicare experience. One independent broker. Direct access — before, during, and after enrollment.
William answers his own phone.
When you call, you reach William directly — not a call center, not a rotating representative, not a voicemail queue.
Help before you enroll.
William explains your options, compares the plans available through the carriers he represents, and helps you choose coverage that fits your doctors, prescriptions, and budget.
Help during enrollment.
William walks you through the application process and makes sure your coverage is confirmed before your effective date.
Support after enrollment.
Questions don't end when the policy starts. William remains available when your coverage circumstances change, when you have billing questions, or when you want to review your options.
No carrier bias.
As an independent broker, William represents multiple insurance companies — not just one. His goal is to find the right fit for you, not to hit a quota for a single carrier.
No cost. No obligation. No pressure.
William's assistance — before, during, and after enrollment — is provided at no direct cost to you. Carriers compensate independent brokers; you do not pay a separate fee for William's guidance. There is no obligation to enroll, and no pressure to choose any particular plan.
No call centers · No carrier bias · Licensed in 22 states
Three ways William can help
I personally return every call. — William Gray
What Clients Say
"I contacted William to assist my wife and I after moving to Florida from another state. He contacted us immediately and scheduled a phone appointment for the following week. We spent about an hour getting to know each other and our needs. He recommended several companies to match our needs and our location here in FL that we would NEVER had figured out on our own. Praise the Lord for Bill and for his help!! I would recommend him to anyone and everyone!!"
Jim M.
Medicare client · Verified Google Review
"Working with William Gray on my Medicare selections was an outstanding experience. Navigating Medicare can feel overwhelming, but William made the entire process simple, clear, and stress-free. He took the time to understand my specific needs, explained every option in a way that was easy to grasp, and offered thoughtful guidance without ever making me feel rushed or pressured."
Julie K.
Medicare client · Verified Google Review
"ABSOLUTELY GOD SENT! I knew nothing about Medicare and close to panicking before speaking with William. Super professional, well informed and kind! Anyone out there approaching 65 years old needs someone like William in their corner; he walked me through each step and all the options best suited my needs!!! All at NO COST because he is paid through the insurance companies."
JKC
Medicare client · Verified Google Review
"Navigating the healthcare system is complex to say the least. This is where The Medicare Dude, William Gray, shined for us on the road to consummating an ideal configuration for our unique and collective situations. William is not just a registered healthcare broker professional, but he is also a wealth of knowledge and sage consult in our best interests. He's always available when questions arise."
TinaKelvin B.
Medicare client · Verified Google Review
"I required an insurance broker with comprehensive knowledge in the field, and William Gray exceeded my expectations. He visited my home and provided a thorough explanation of various Medicare products. As a result, he helped me select the best supplement and achieve a significant reduction of over $150 per month in premiums."
Debra A.
Medicare client · Verified Google Review
"Very Knowledgable and personable! William made a seemingly difficult transition easy and seamless. I appreciated his unbiased opinion and personalized what was best for me. He took great care in listening to my concerns. I never felt rushed and felt he took a personal interest in assisting me to make the best choice. Not one of those "Big box" sales as seen on TV. Highly recommend William."
Sharon H.
Medicare client · Verified Google Review
Showing 6 of 94 verified Google reviews
Talk Directly With William About Medicare Supplement Coverage in Jacksonville
No pressure. No cost. Just honest guidance from an independent agent who works for you — not an insurance company.
Prefer to talk? Call William — 1-800-DUDE-309 (800-383-3309)
Licensed in multiple states · Independent · No cost to you